Home Buyers
How do I compare two Houston homes in different ZIP codes?
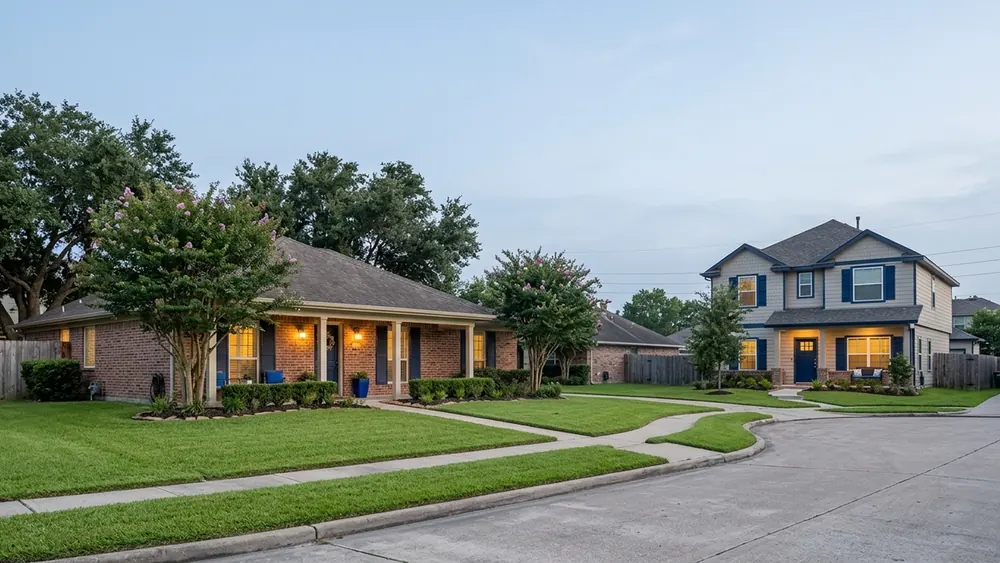
Compare the two homes on the same points: your commute, total monthly cost, condition and age, HOA rules, the actual jurisdiction, and official tax and flood records. A ZIP code is a mailing label, not a verdict, so check each home on its own record.
On this page
Compare the homes, not the ZIP codes
Compare two homes in different ZIP codes by putting them side by side on the same list: your commute, the full monthly cost, condition and age, HOA rules, the actual jurisdiction, and the official records for taxes and flood information. The ZIP code itself tells you very little. It is a mailing label, and the facts that affect your daily life and your budget belong to the individual home, not to the number on the envelope.
This matters because ZIP codes invite shortcuts. It is easy to assume one ZIP code is pricier, newer, or more convenient than another and let that assumption make the choice for you. Those generalizations do not hold for every street, and they say nothing about the specific house in front of you. A fair comparison looks past the label to the home, the lot, the records, and how the home fits your week.
It also matters because a ZIP code does not follow a city line. A single ZIP code can cross city limits, taxing districts, and school district boundaries, and a listing site may show a mailing city that is not the jurisdiction the home actually sits in. Two homes that look like neighbors on a map can sit under different rules, while two homes far apart can share more than you expect.
Why a ZIP code is only a mailing label
ZIP codes were drawn to deliver mail, not to describe homes. That is why they make a weak comparison tool on their own. When you see two listings in different ZIP codes, treat the number as a prompt to look closer, not as a summary of what you will get. The real questions are about the specific address: which city it belongs to, which districts tax it, and what its records show.
In Houston this can come up when a listing site shows a neighboring city’s name for an address that sits inside the City of Houston, or a mailing city for a home outside city limits. The label on the listing is not the final word. City limits can affect property taxes, city services, and school assignment, so the jurisdiction is worth confirming for both homes before you weigh one against the other.
Official records settle it. The city can confirm whether an address sits inside its limits, the county appraisal district shows the taxing jurisdictions attached to a property, and the school district confirms assignment for a specific address. Boundaries and assignments change over time, so check each home directly rather than relying on what a listing, a neighbor, or an old search result says about the area around it.
Line up the full monthly cost
Price is only the starting point. Two homes with similar asking prices can carry very different monthly costs once you add property taxes, insurance, HOA dues, and any special district assessments. Those amounts vary by property and change over time, so do not estimate them from the ZIP code or a neighbor’s bill. Gather the actual figures for each home from the sources that set them, and write them in the same place.
The county appraisal district is the place to look at tax records and the taxing jurisdictions on a property. An insurance agent can quote coverage for each specific home, which can differ based on the home and its location. The HOA documents show dues and rules, and a title company can help identify what is recorded against the property. A lender then ties it together into a payment you can compare.
When you put the two monthly totals side by side, the comparison often looks different from the one the asking prices suggested. That is the point of doing it. A home that looked like a stretch can turn out to be closer to your range, or the reverse. Either way, you are now comparing what you would actually pay each month instead of what a listing headline implies.
Check condition, age, and what comes with each
Next, compare the homes themselves. If one is a newer build and the other is an established resale home, the comparison widens. A new build may come with builder warranty paperwork and an expected completion date, while a resale home has a history you can inspect and a disclosure you can read. Neither is automatically the right choice. Line up the same points for both so the real differences become visible.
- Age and overall condition, checked by a licensed home inspector
- What is included with the home, from appliances to window coverings and fencing
- Completion stage and warranty paperwork for a newer build, confirmed with the builder
- Seller’s disclosure details for a resale home, read closely and questioned where unclear
Write these down for each home in the same order. It sounds simple, but it prevents a common comparison mistake: remembering the kitchen of one home and the yard of the other, and blending them into a picture that neither home actually matches. A consistent list keeps each house honest, and it makes the trade-offs between them much easier to talk through with anyone buying with you.
A side by side worksheet for both homes
Use a simple table to keep the comparison fair. For each question, note why it matters and who gives the official answer, then add a column of your own for each home. The table below is a starting point. Add rows for anything specific to your situation, such as a commute you share with someone else or a feature you will not give up under any circumstances.
| Question | Why it matters | Who to ask |
|---|---|---|
| Which city is the home actually in | City limits can affect taxes, services, and school assignment | The city and the county appraisal district |
| What are the taxes and taxing districts | They change the monthly cost between similar prices | The county appraisal district |
| What do flood records show for the home | Coverage and decisions depend on the specific property | FEMA flood maps, the disclosure, an insurance agent |
| What do the HOA documents require | Dues and rules vary by community and change | The HOA documents and a title company |
| How does the commute work in real traffic | It shapes your weekday more than a ZIP code | You, testing the route at real hours |
Fill in the table as you go rather than at the end. Some answers arrive quickly, and others take a phone call or a records search. When a cell stays blank, that is useful too: it tells you exactly what to ask before you make an offer. Records change, so confirm every answer for the specific address rather than assuming it carries over from a nearby home.
Test the commute from each address
A commute can look similar on a map and feel very different on a weekday. Drive or ride the route from each address at the hours you would actually travel, and do it more than once if you can. Times vary, so treat any estimate from a listing or an app as a rough guess until you have tested it yourself, in the conditions you will really face.
Then put the commute on the same page as cost and condition. A home with a lower monthly cost and a harder commute is a real trade-off, and only you can weigh it. The goal is not to find a winner between two ZIP codes. It is to see clearly what each home asks of you, so the final choice reflects how you actually live rather than how a label sounds.
What to gather before you choose
Before you choose between the two homes, gather the pieces that turn a feeling into a comparison. You do not need every answer at once, but you should know which ones are still missing. A short folder for each home, paper or digital, keeps the documents straight and makes it easy to see where one home has answers and the other still has questions.
- Current listing records for both homes, checked for status and details
- Tax records and taxing jurisdictions from the county appraisal district
- HOA documents, the seller’s disclosure, and flood information for each address
- Your tested commute notes and a payment range confirmed with a lender
Mardis works with buyers across Houston, with recent work in south and southeast Houston and in Missouri City, and can help you build this comparison for the specific homes you are considering. It is a calm, step by step process, and it starts with whatever you already have. Which of the two homes still has the most blank cells in your table, and what is the first question you could answer?
This article is general information about buying and selling homes in Houston, Texas. It is not legal, tax, lending, insurance, inspection or valuation advice and does not predict prices or promise results. Confirm builder terms with the builder and the contract, city limits and school assignment with the city and school district, taxes and special districts with the appraisal district, flood information with official sources, contracts with a real estate attorney, and financing with a lender. Mardis Ventura, SERHANT. Equal Housing Opportunity.
Written by